The 3% Fee Trap: How a $100,000 Credit Card Plan Costs $3,000 Up Front
Zero interest credit card funding means using 0% promo offers to borrow cash for free, but stacking dozens of cards to chase $1 million is a trap if you cannot repay before the promo ends.
Cards often charge 3% to 5% up front, and rates can jump above 20% after the promo.
Banks also watch how many cards you open, and personal guarantees can put your own money at risk.
👉Free download : Start a 1-Person Business With Claude AI — Free Quick-Start Guide
Table of Contents
The Pitch That Made Me Stop Scrolling
I thought I understood credit cards.
You swipe, you pay, and you try not to carry a balance.
Then I listened to a funding coach on a business podcast, and the story sounded very different.
He said you can stack many 0% cards and raise $500,000 or more in working cash.
He said you can repeat the process every six months.
He also described one student who opened 13 cards in 10 days and kept about $15,600 in sign-up bonuses.
Those are his claims, and I could not verify them, so treat them as a sales pitch and not a promise.
Still, the idea behind zero interest credit card funding is real, and it deserves a careful look.
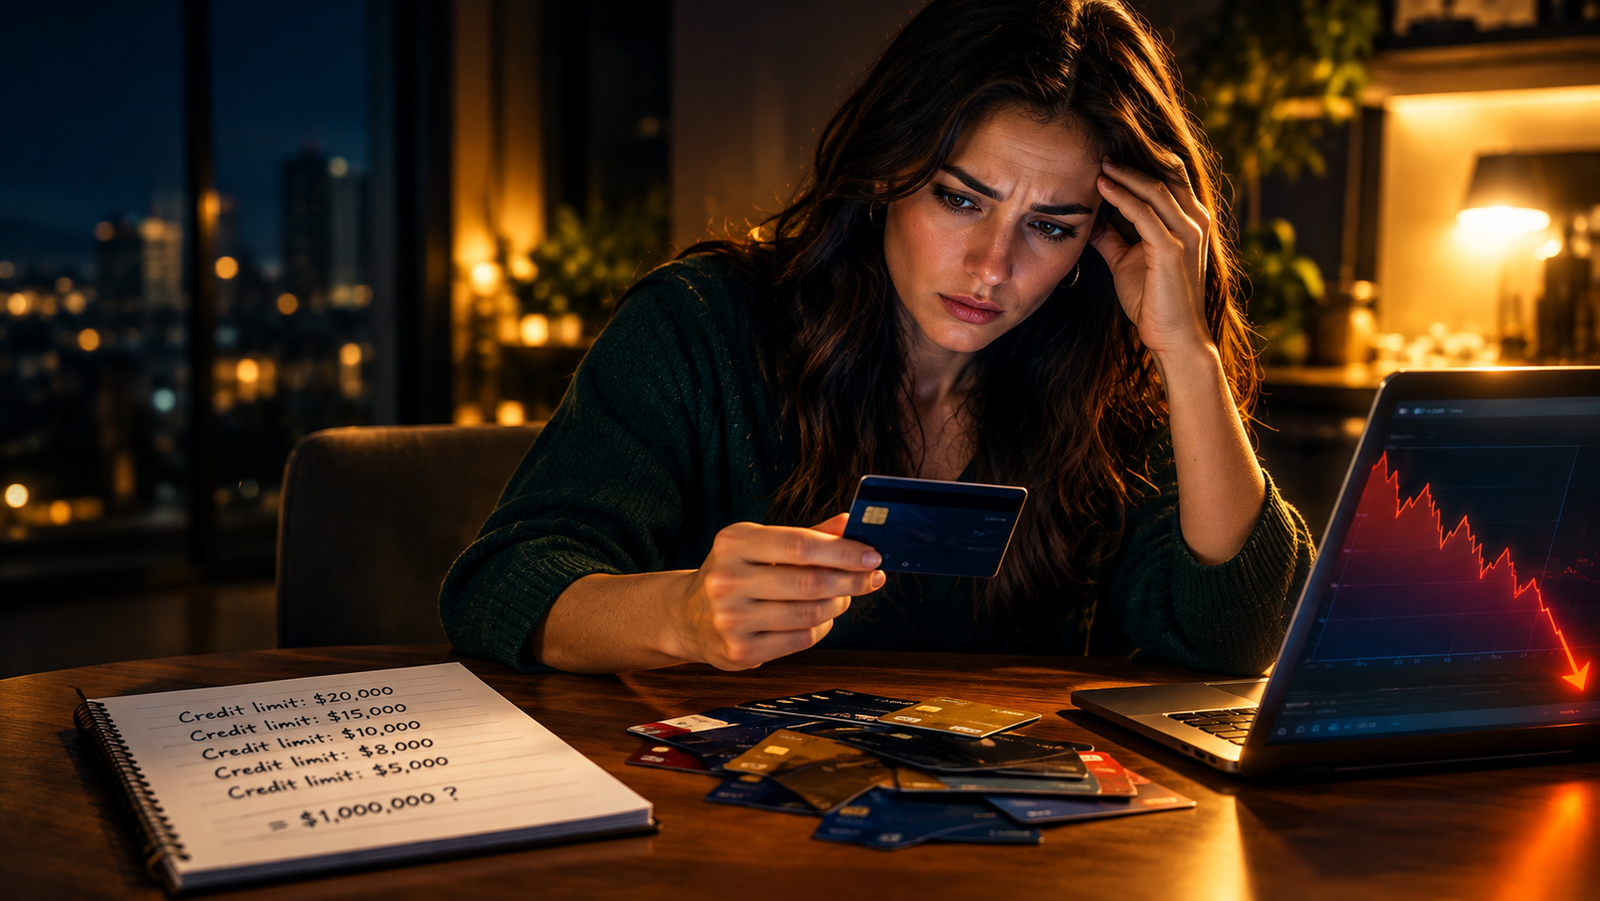
Picture a kitchen table late at night.
A laptop glows next to a cold cup of tea.
On the screen sit a dozen tabs, each one a different bank offer.
A notepad lists credit limits in blue ink: $20,000, $35,000, $50,000.
The numbers look like free money.
That picture is exactly why this topic spreads so fast online.
Big numbers feel like freedom, and nobody likes talking about the bill that arrives later.
So let us talk about the bill, the rules, and the smart way to think about zero interest credit card funding.
How Zero Percent Cards Really Work
A 0% intro APR card charges no interest for a set time.
That time is often 12 to 21 months, depending on the card.
You still must pay the minimum every month.
If you miss one, you can lose the promo rate.
Many cards also charge a balance transfer fee, usually 3% to 5%.
On $40,000, a 3% fee costs $1,200, and a 5% fee costs $2,000.
That fee is the true price of this kind of zero interest credit card funding.
It is cheap compared to most loans, but it is never free.
Cash advances work differently from balance transfers.
Most cards charge a cash advance fee and start interest right away, often at a much higher rate.
So the words you use matter less than the terms printed on your offer.
Look for the phrase “promotional APR” and check whether it covers transfers.
Also watch for deferred interest, which works in a harsher way.
With deferred interest, one unpaid dollar at the end can bring back all the old interest.
Many true 0% APR cards do not work that way, but store cards often do.
Always check which kind you have before starting any zero interest credit card funding plan.
New purchases can also cause trouble.
If you carry a balance, you may lose the grace period on new buys.
Many people keep the cash card locked in a drawer for that reason.
Business owners often ask where to form a company before they apply for business cards.
Services like Bizee (formerly Incfile) and ZenBusiness can file an LLC for a fee plus state costs.
An LLC does not unlock zero interest credit card funding by itself, but it keeps business and personal money apart.
If you want a plan for the business itself, not only the cash, start there.
👉Get Access to the full Package: Start a 1-Person Business With Claude AI shows how to build a one-person business with Claude before you borrow a cent.
Why Banks Say No: The 5/24 and 2/30 Rules
Banks watch how often you apply.
The best-known rule is called Chase 5/24.
Credit card writers report that Chase often says no if you opened five or more personal cards in the past 24 months.
Chase has not published this as an official rule, so treat it as common knowledge and not as law.
Another reported rule, called 2/30, says two Chase approvals in 30 days may block a third.
Each application also adds a hard inquiry to your credit report.
Inquiries stay on your report for two years, though FICO looks mostly at the last 12 months.
That is why zero interest credit card funding works best as a slow plan and not a race.
The coach sorted banks into three groups.
Big banks come first, such as Chase, Bank of America, Wells Fargo, Citi, Capital One, and American Express.
Regional banks come next, and local credit unions come last.
Credit unions are member-owned, and many offer lower rates, but each one has its own rules.
He said some big banks approve large limits with little paperwork.
Limits really depend on your income, your score, and your history with that bank.
No bank owes you a set amount, and nothing in zero interest credit card funding guarantees a number.
A bank that sees tiny limits on your old cards may wonder why anyone should trust you with more.
Honesty matters at this step.
Every application asks about your income, and the answer must be true.
Giving false information to a federally insured bank can be a federal crime under 18 U.S.C. § 1014.
The coach talked about staying under each bank’s paperwork limit.
That is fine if your numbers are real, but it is a bad idea if you stretch the truth.
Think of the application like a handshake with a very large, very careful lawyer.
A clean file today makes the next approval easier.
Even a smart zero interest credit card funding plan falls apart when the facts do not hold up.
The Credit Score Myths Hidden Inside the Pitch
What FICO Really Counts
Many pitches promise an 800 score in 30 days.
No honest person can promise that.
FICO publishes five parts of your score.
Payment history counts 35%, amounts owed count 30%, length of history counts 15%, new credit counts 10%, and credit mix counts 10%.
The coach is right that history length, mix, and amounts owed together make up 55%.
But FICO does not publish a magic target such as 21 accounts or a nine-year average age.
Using less than 30% of each limit is a common rule, and many top scorers stay near 10%.
Issuers report your balance on the statement date, so paying before it closes can lower the number lenders see, a small habit that helps any zero interest credit card funding plan.
Picture a round pie chart pinned to a fridge.
The biggest slice is bright green and says payment history.
The second slice is deep blue and says amounts owed.
Three thin slices in orange, purple, and gray cover age, new credit, and mix.
Late payments hit that green slice the hardest.
That is why fixing late payments beats any trick for adding accounts.
The coach warned that polish without repair does not work.
I agree, because banks look at the whole file and not just the shiny parts.
The Authorized User Tradeline Trap
Being an authorized user means you are added to someone else’s credit card.
If a parent or spouse has an old card with a clean record, their history can show on your report.
That simple version is common and low risk when you trust the person.
The coach also described renting a stranger’s old card for about 60 days for a fee.
He said it is legal and ethical, but lenders and regulators have raised concerns about the practice, so ask a licensed attorney first.
You would share your full name, birth date, and Social Security number with someone you may never meet.
If that card shows a late payment or a high balance, the damage lands on your report too.
Weigh that risk carefully before buying any boost for your zero interest credit card funding goals.
Credit Repair: What the Law Actually Gives You
You do not need to buy a miracle to fix errors.
The Fair Credit Reporting Act lets you dispute wrong items for free.
You can pull your reports each week at AnnualCreditReport.com.
Then you can dispute errors with Equifax, Experian, and TransUnion.
The bureaus generally must investigate within 30 days.
Most negative items fall off after seven years, and bankruptcies can stay up to ten.
Paying a collection does not erase it, though newer scoring models treat paid collections better.
Many lenders still use older models, so clean reports matter before any zero interest credit card funding application.
Be careful with companies that promise fast results.
The Credit Repair Organizations Act bans false promises and, generally, charging before work is done.
Picture a manila folder on your desk with a highlighted report, a printed letter, and a green certified mail receipt clipped to the front.
That folder is your paper trail.
You can ask Claude to help draft a dispute letter, then check every fact yourself before you send it.
The coach also mentioned suing the bureaus.
Small claims court is one option, but get legal advice first because every case is different.
Slow, honest, documented steps beat shortcuts almost every time.
The Math Nobody Puts in the Ad
Let us run a simple example.
Say you move $100,000 onto 0% cards and pay a 3% fee.
That fee is $3,000 on day one.
Say the promo lasts 18 months, and you repay half.
The other $50,000 now faces a regular rate, and Federal Reserve data have shown average card rates above 20%.
At 21%, that balance costs about $10,500 a year, or $875 a month.
This is where zero interest credit card funding turns from a tool into a trap.
The cliff comes fast, and the fee was only the start.
Sign-up bonuses are not free cash either.
Most bonuses need a minimum spend, often thousands of dollars in the first three months.
Balance transfers usually do not count toward that spend.
Business cards often require a personal guarantee, which means you owe the money if the business cannot pay.
The CARD Act’s protections mostly cover consumer cards, not business ones.
Banks can also cut limits or close accounts when they see risk.
If your plan needs every card to stay open, it is too fragile.
Build zero interest credit card funding on a plan B, not on hope.
Smart Ways to Use Zero Percent Without Falling In
Start with the end date.
Write down the day the promo ends and set alerts 60 days before.
Set autopay for more than the minimum.
Borrow only what you can repay from cash flow, not from a future win.
Keep a cash buffer for several months of payments.
Some people park cash in a CD or Treasury bills through TreasuryDirect, but the fee can eat most of the earnings.
A 3% fee is a high hurdle when yields are only a few percent a year.
Done well, zero interest credit card funding is a short bridge and not a long road.
Real estate was the coach’s favorite use.
He likes the BRRRR method, which means buy, rehab, rent, refinance, and repeat.
It can work, but repairs can run over budget and a refinance is never guaranteed.
Many mortgage lenders also check where your down payment came from.
Borrowed money can raise questions, so ask your lender before you plan around cards.
Picture a half-built house with open wall frames, a blue tarp on the roof, and a contractor’s invoice taped to a sawhorse.
Every one of those details costs real cash that must come from somewhere.
Smart zero interest credit card funding leaves room for surprises like that.
Other tools can be safer.
SBA microloans offer up to $50,000 through nonprofit lenders.
A local credit union may offer a small business line of credit.
Some banks offer business cards with an intro 0% APR on new purchases.
Compare the true cost of each option, including fees, on one simple page.
Write the total payback number on a sticky note and put it on your monitor.
If that number makes your stomach drop, borrow less.
Choose the smallest loan that solves the problem, even inside zero interest credit card funding.
Start Smaller: Build Income Before You Borrow
The best debt is the debt you barely need.
A one-person digital business can start with a laptop and a small budget.
That is why many creators skip big loans and begin with content and simple products.
Fewer dollars borrowed means less stress when the promo clock runs out.
If you write a blog, you can learn to earn from it one step at a time.
👉Get Access to : The AI Blog Monetization Quickstart Guide shows a simple path from posts to income with AI.
Fix the income first, and zero interest credit card funding becomes a small helper and not your whole plan.
That order protects your sleep.
Final Thoughts: The Real $1M Lesson
So what did I learn?
The $1M money trap is not the card itself.
The trap is believing the biggest limit equals the best plan.
Zero interest credit card funding can help when you borrow small, repay fast, and tell the truth on every form.
It hurts when you stack cards, chase bonuses, and hope the future fixes the bill.
Check your reports, protect your score, and compare every fee in writing.
I am not a lawyer or a financial advisor, so talk to a licensed pro about your own case.
Slow and honest wins this game.
Here is a simple plan for this week.
Pull your free reports and write down every error.
List your current cards, limits, and balances on one page.
Pick a goal that needs cash and price it honestly.
Decide how you would repay it if the promo ended tomorrow.
Then, and only then, look at offers.
Your future self will thank you for choosing zero interest credit card funding with a clear exit.
Start small, stay honest, and keep the exit door open.
👉Free download : Start a 1-Person Business With Claude AI — Free Quick-Start Guide
👉Free download : The Claude AI Digital Product Starter Pack — 10 Done-For-You Prompts for Beginners

We strongly recommend that you check out our guide on how to take advantage of AI in today’s passive income economy.